Pune's Bank of Maharashtra posts Rs 2,310 crore profit, gross NPA at 1.25%
 By Siddharth VermaBusiness Correspondent, Peepals Bharat
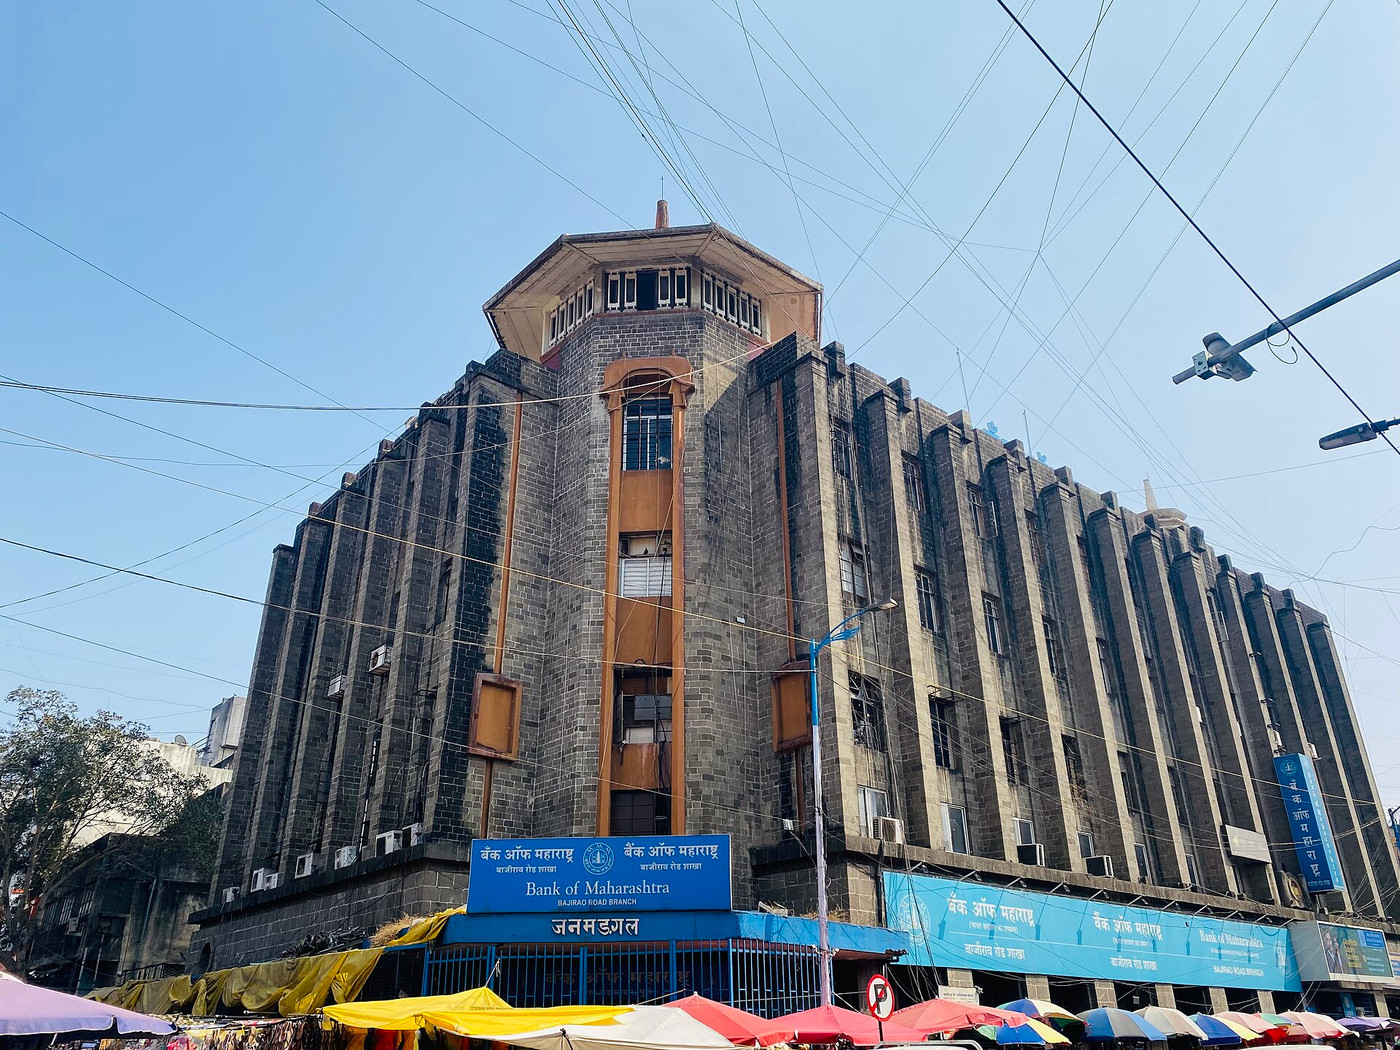
File photo: Ganesh Dhamodkar (CC BY 4.0), via Wikimedia Commons
Pune-based Bank of Maharashtra's September-quarter profit rose 41.42% to Rs 2,310 crore, with gross NPAs down to 1.25%, results approved on 26 October 2026 show.
What Happened
Bank of Maharashtra, the Pune-headquartered public sector bank, reported a standalone net profit of Rs 2,309.59 crore for the July-September quarter of 2026-27, up 41.42% from Rs 1,633 crore a year earlier. Its board approved the results on Monday, 26 October 2026. The bank's total business grew 25.16% to Rs 7,05,766 crore, and its gross non-performing assets, loans that borrowers have stopped repaying, fell to 1.25% of total loans from 1.72% a year ago.
Key Facts
- Net profit: Rs 2,309.59 crore in Q2 FY27, up 41.42% from Rs 1,633 crore in Q2 FY26.
- Net interest income (the difference between interest earned on loans and interest paid on deposits): Rs 3,954 crore, up 21.76% from Rs 3,248 crore.
- Operating profit: Rs 3,368.67 crore; total income Rs 9,735.41 crore.
- Total business (deposits plus advances): Rs 7,05,766 crore, up 25.16% year on year.
- Gross NPA: 1.25% on 30 September 2026, down from 1.72% a year earlier and 1.45% at the end of June 2026.
- Net NPA: 0.12%, down from 0.18% a year earlier.
- Capital adequacy ratio (Basel III): 18.51%; first-half profit: Rs 4,329.78 crore.
Why It Matters
Bank of Maharashtra is one of the smaller public sector banks by size, but in recent years it has been among the fastest-growing state-owned lenders. This quarter's numbers continue that pattern: business growing by a quarter in a year, profit rising faster than interest income, and bad loans shrinking. Interest income alone grew about 22%, while profit grew about 41%, showing that lower bad-loan costs and higher other income did much of the work.
The fall in gross NPAs to 1.25% and net NPAs to 0.12% matters because it means the bank needs to set aside less money for bad loans, which feeds directly into profit. A capital adequacy ratio of 18.51%, well above the regulatory minimum, gives it room to keep lending without immediately needing fresh capital from the government. Capital adequacy measures how much of its own capital a bank holds against the risk in its loans; the higher it is, the more losses the bank can absorb.
For Maharashtra, where the bank has its deepest branch network, its growth means more credit for small businesses, farmers and home buyers in the state. Strong results at public sector banks also matter to taxpayers, because the government is their majority owner and receives dividends when they earn profits.
The results come during a strong September quarter for state-run lenders. Bank of India and Indian Overseas Bank also reported sharply higher profits for the quarter, helped by lower bad-loan provisions and steady loan growth.
| Measure | Q2 FY26 | Q2 FY27 |
|---|---|---|
| Net profit | Rs 1,633 crore | Rs 2,309.59 crore |
| Net interest income | Rs 3,248 crore | Rs 3,954 crore |
| Gross NPA | 1.72% | 1.25% |
| Net NPA | 0.18% | 0.12% |
Impact
Short-term: Higher profit, a first-half profit of Rs 4,329.78 crore and cleaner books strengthen the bank's position to grow loans in the second half of the year, including the festive season, when demand for retail and vehicle loans usually rises.
Long-term: If asset quality holds, Bank of Maharashtra can fund more of its growth from its own profits, reduce its dependence on government capital, and keep competing with larger banks on loan rates.
Who is affected: The bank's customers and borrowers, especially in Maharashtra; its employees; shareholders, including the Government of India as majority owner; and small businesses and farmers who rely on public sector banks for credit.
Key Takeaway
Bank of Maharashtra's Q2 FY27 profit rose 41.42% to Rs 2,309.59 crore as total business grew 25% and gross NPAs fell to 1.25%, results approved on 26 October 2026 show.
Questions and Answers
What was Bank of Maharashtra's Q2 FY27 profit?
Bank of Maharashtra reported a standalone net profit of Rs 2,309.59 crore for the quarter ended 30 September 2026, up 41.42% from Rs 1,633 crore a year earlier.
How much bad debt does Bank of Maharashtra have?
Its gross non-performing assets were 1.25% of loans on 30 September 2026, down from 1.72% a year earlier. Net NPAs, after provisions, were 0.12%.
How fast is Bank of Maharashtra's business growing?
Total business, which is deposits plus advances, grew 25.16% year on year to Rs 7,05,766 crore at the end of September 2026.
What is net interest income?
Net interest income is what a bank earns as interest on its loans minus the interest it pays depositors. Bank of Maharashtra's rose 21.76% to Rs 3,954 crore in the quarter.
Disclaimer: Prepared by the Peepals newsroom from publicly available sources with AI assistance. Information is accurate to the best of our knowledge at the time of publication and may change. Images may be representative. Not professional advice. Report an error via our contact page.
By Siddharth Verma, Business CorrespondentCovers Business and more for Peepals Bharat. All stories by Siddharth Verma
BP Singh, creator of CID and Aahat, dies at 77 in Mumbai
ECI suspends six officials over lapses in Agra teachers' MLC poll
Get the day's stories in your inbox
Peepals Weekly: the week decoded, free. One email a week, unsubscribe in one click.
Siddharth Verma is a pen name of the Peepals Global Editorial Team, which researches, fact-checks and publishes every story. The portrait is an illustration.